SOCP Portfolio Optimization
Portfolio selection with real-world frictions — transaction costs, variance caps, shortfall-risk limits, diversification bounds — solved exactly and fast as a second-order cone program.
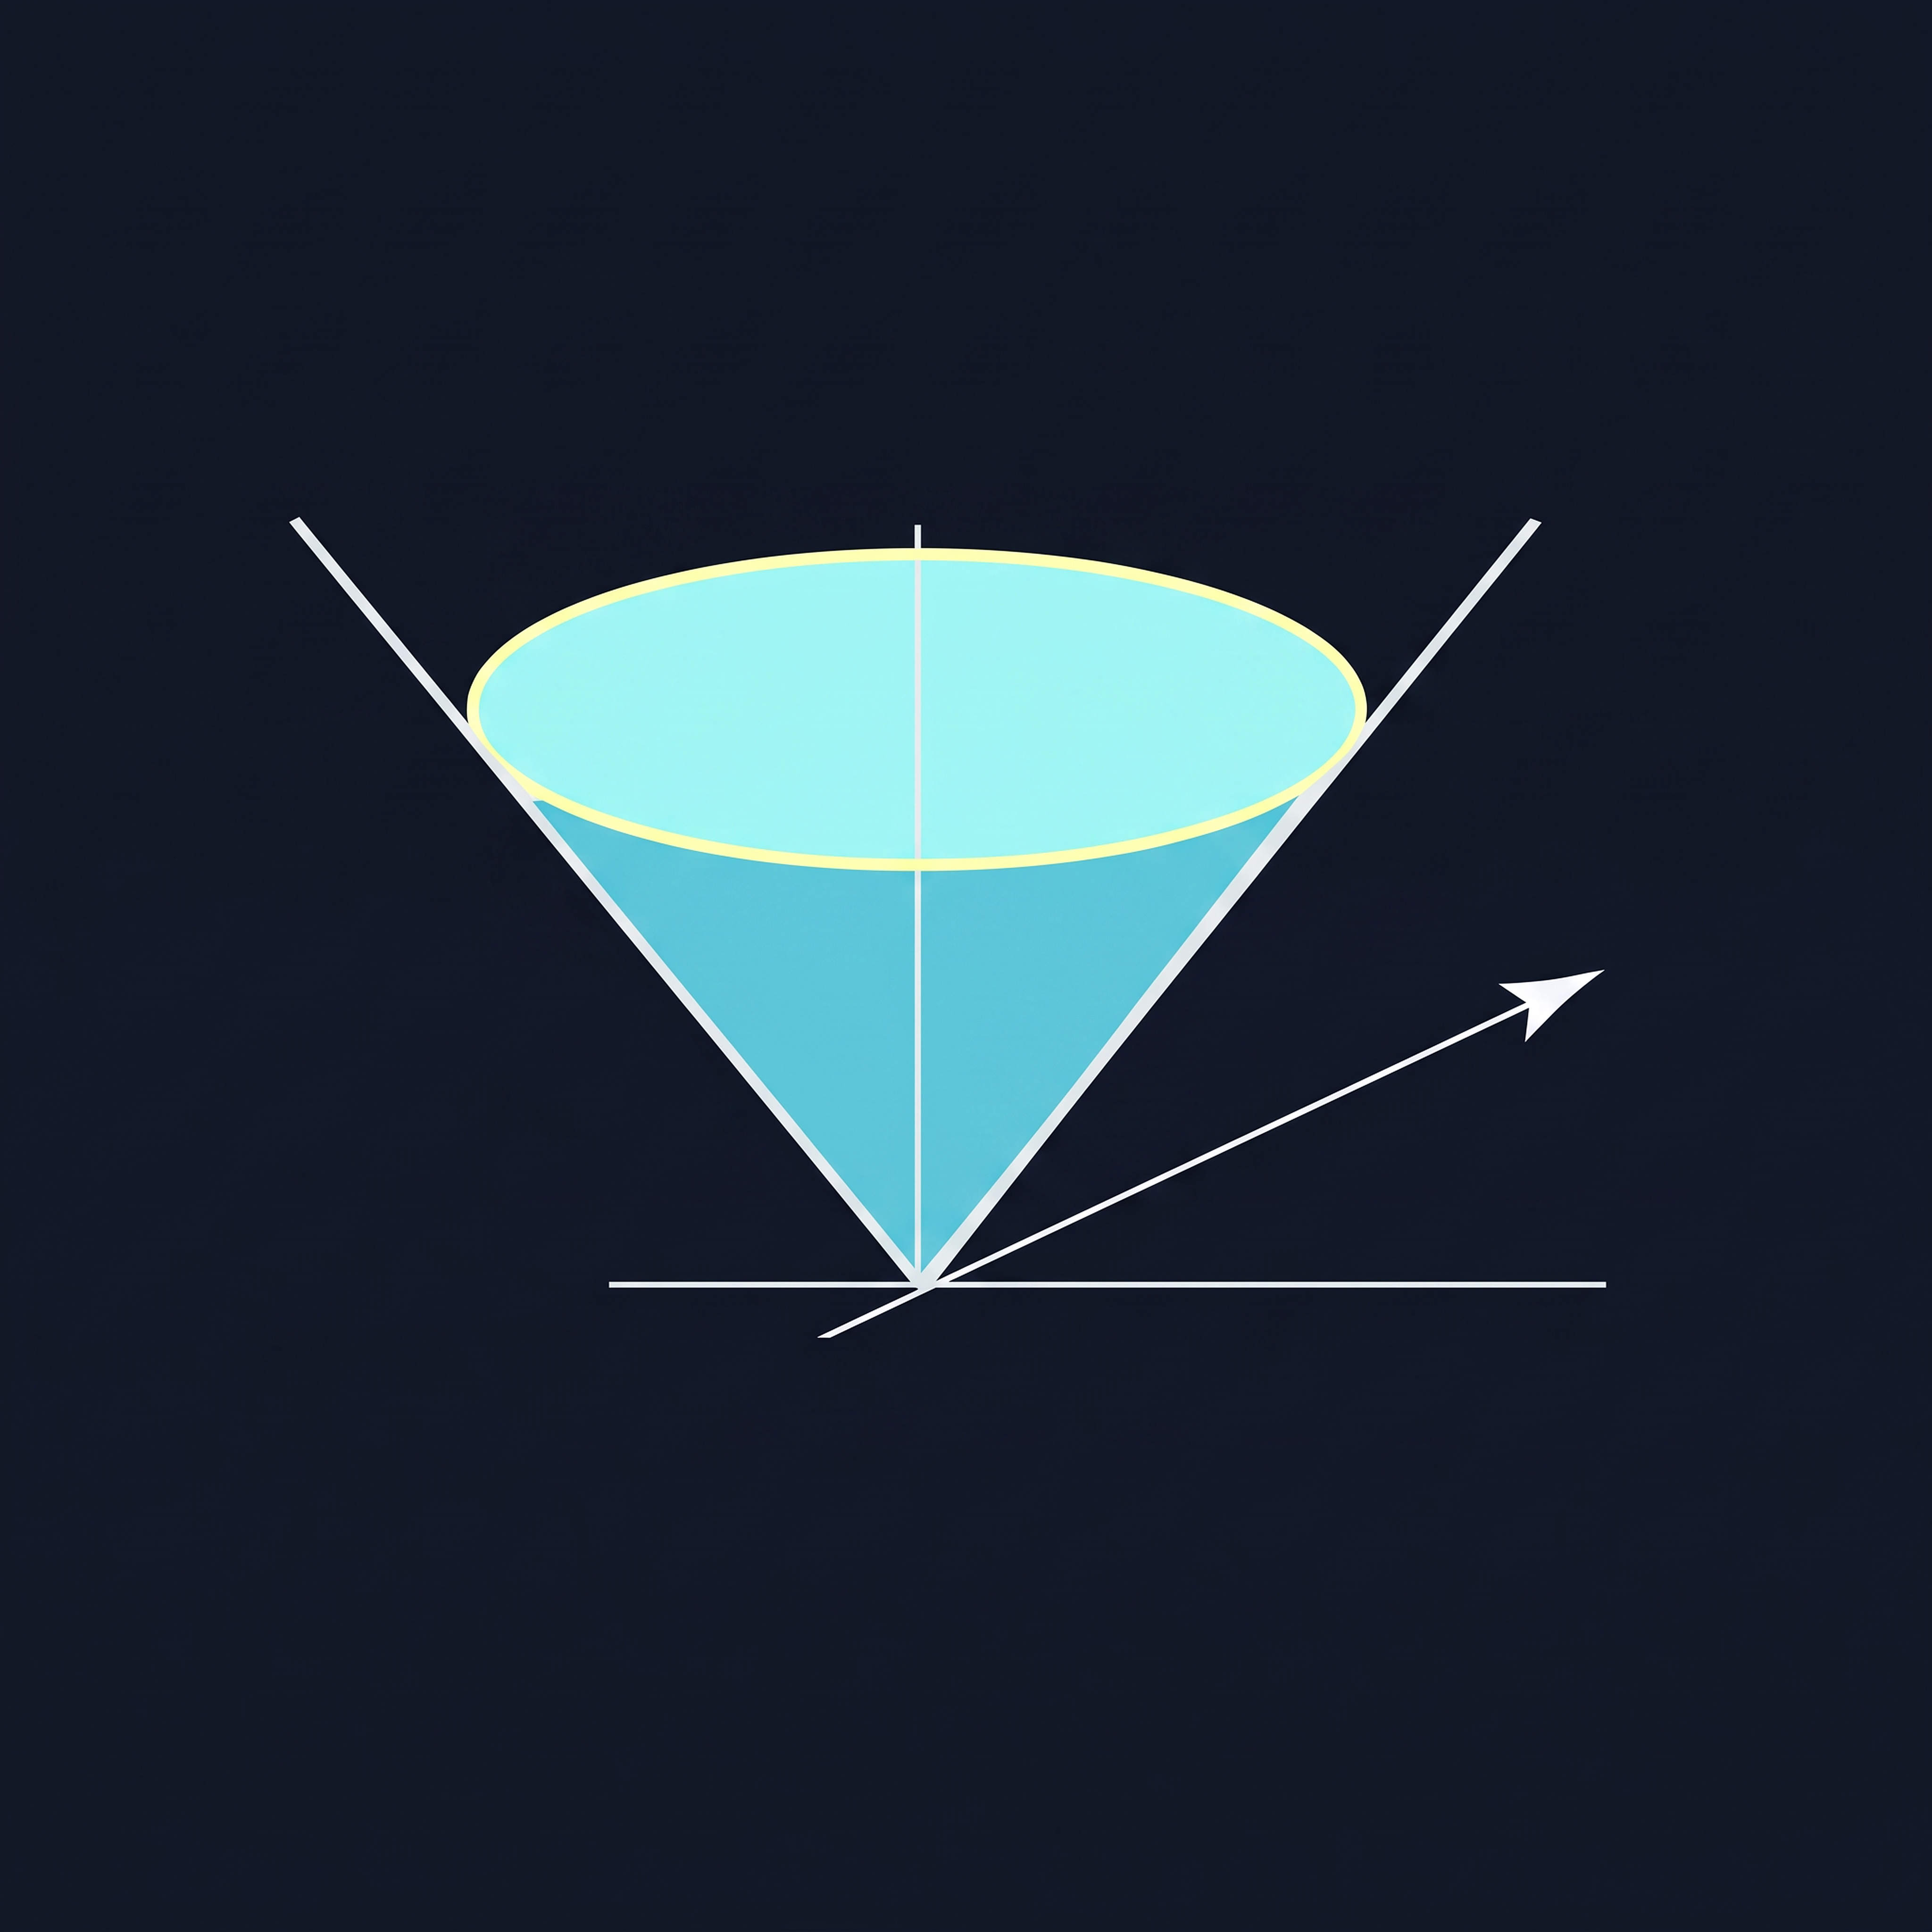
A second-order cone program minimizes a linear objective subject to constraints of the form ‖Aᵢx + bᵢ‖ ≤ cᵢᵀx + dᵢ. It sits in a sweet spot between LP and semidefinite programming: general enough for robust optimization and norm-based constraints, yet solvable by interior-point methods in 5–50 iterations, nearly independent of problem size.
Lobo, Fazel & Boyd show that single-period portfolio selection with linear transaction costs, position and diversification bounds, short-sale limits, a variance cap ‖Σ¹ᐟ²(w+x)‖ ≤ σmax, and Gaussian shortfall-risk (VaR) constraints all reduce to one SOCP — a 100-stock example with two shortfall constraints solves in minutes, exactly and globally.
Fixed (lump-sum) transaction costs make the problem combinatorial and NP-hard. The paper's convex relaxation yields a cheap upper bound on the optimum, and an iterative reweighting heuristic — the same device used in sparse signal recovery — produces near-optimal trade vectors with few nonzero trades, ideal for institutional rebalancing.
Our solver supports transaction costs, turnover, sector and cardinality-style constraints at institutional scale.
References
- Lobo, M. S., Vandenberghe, L., Boyd, S. & Lebret, H. (1998). "Applications of Second-Order Cone Programming." Linear Algebra and its Applications, 284, 193–228. https://web.stanford.edu/~boyd/papers/pdf/socp.pdf
- Lobo, M. S., Fazel, M. & Boyd, S. (2007). "Portfolio Optimization with Linear and Fixed Transaction Costs." Annals of Operations Research, 152, 341–365. https://stanford.edu/~boyd/papers/pdf/portfolio.pdf