Elliott Pairs Trading Model
Gives the pairs-trading heuristic a rigorous probabilistic foundation: the pair's spread is a hidden mean-reverting Markov chain observed in Gaussian noise, and trades fire when the observed spread diverges from its filtered equilibrium.
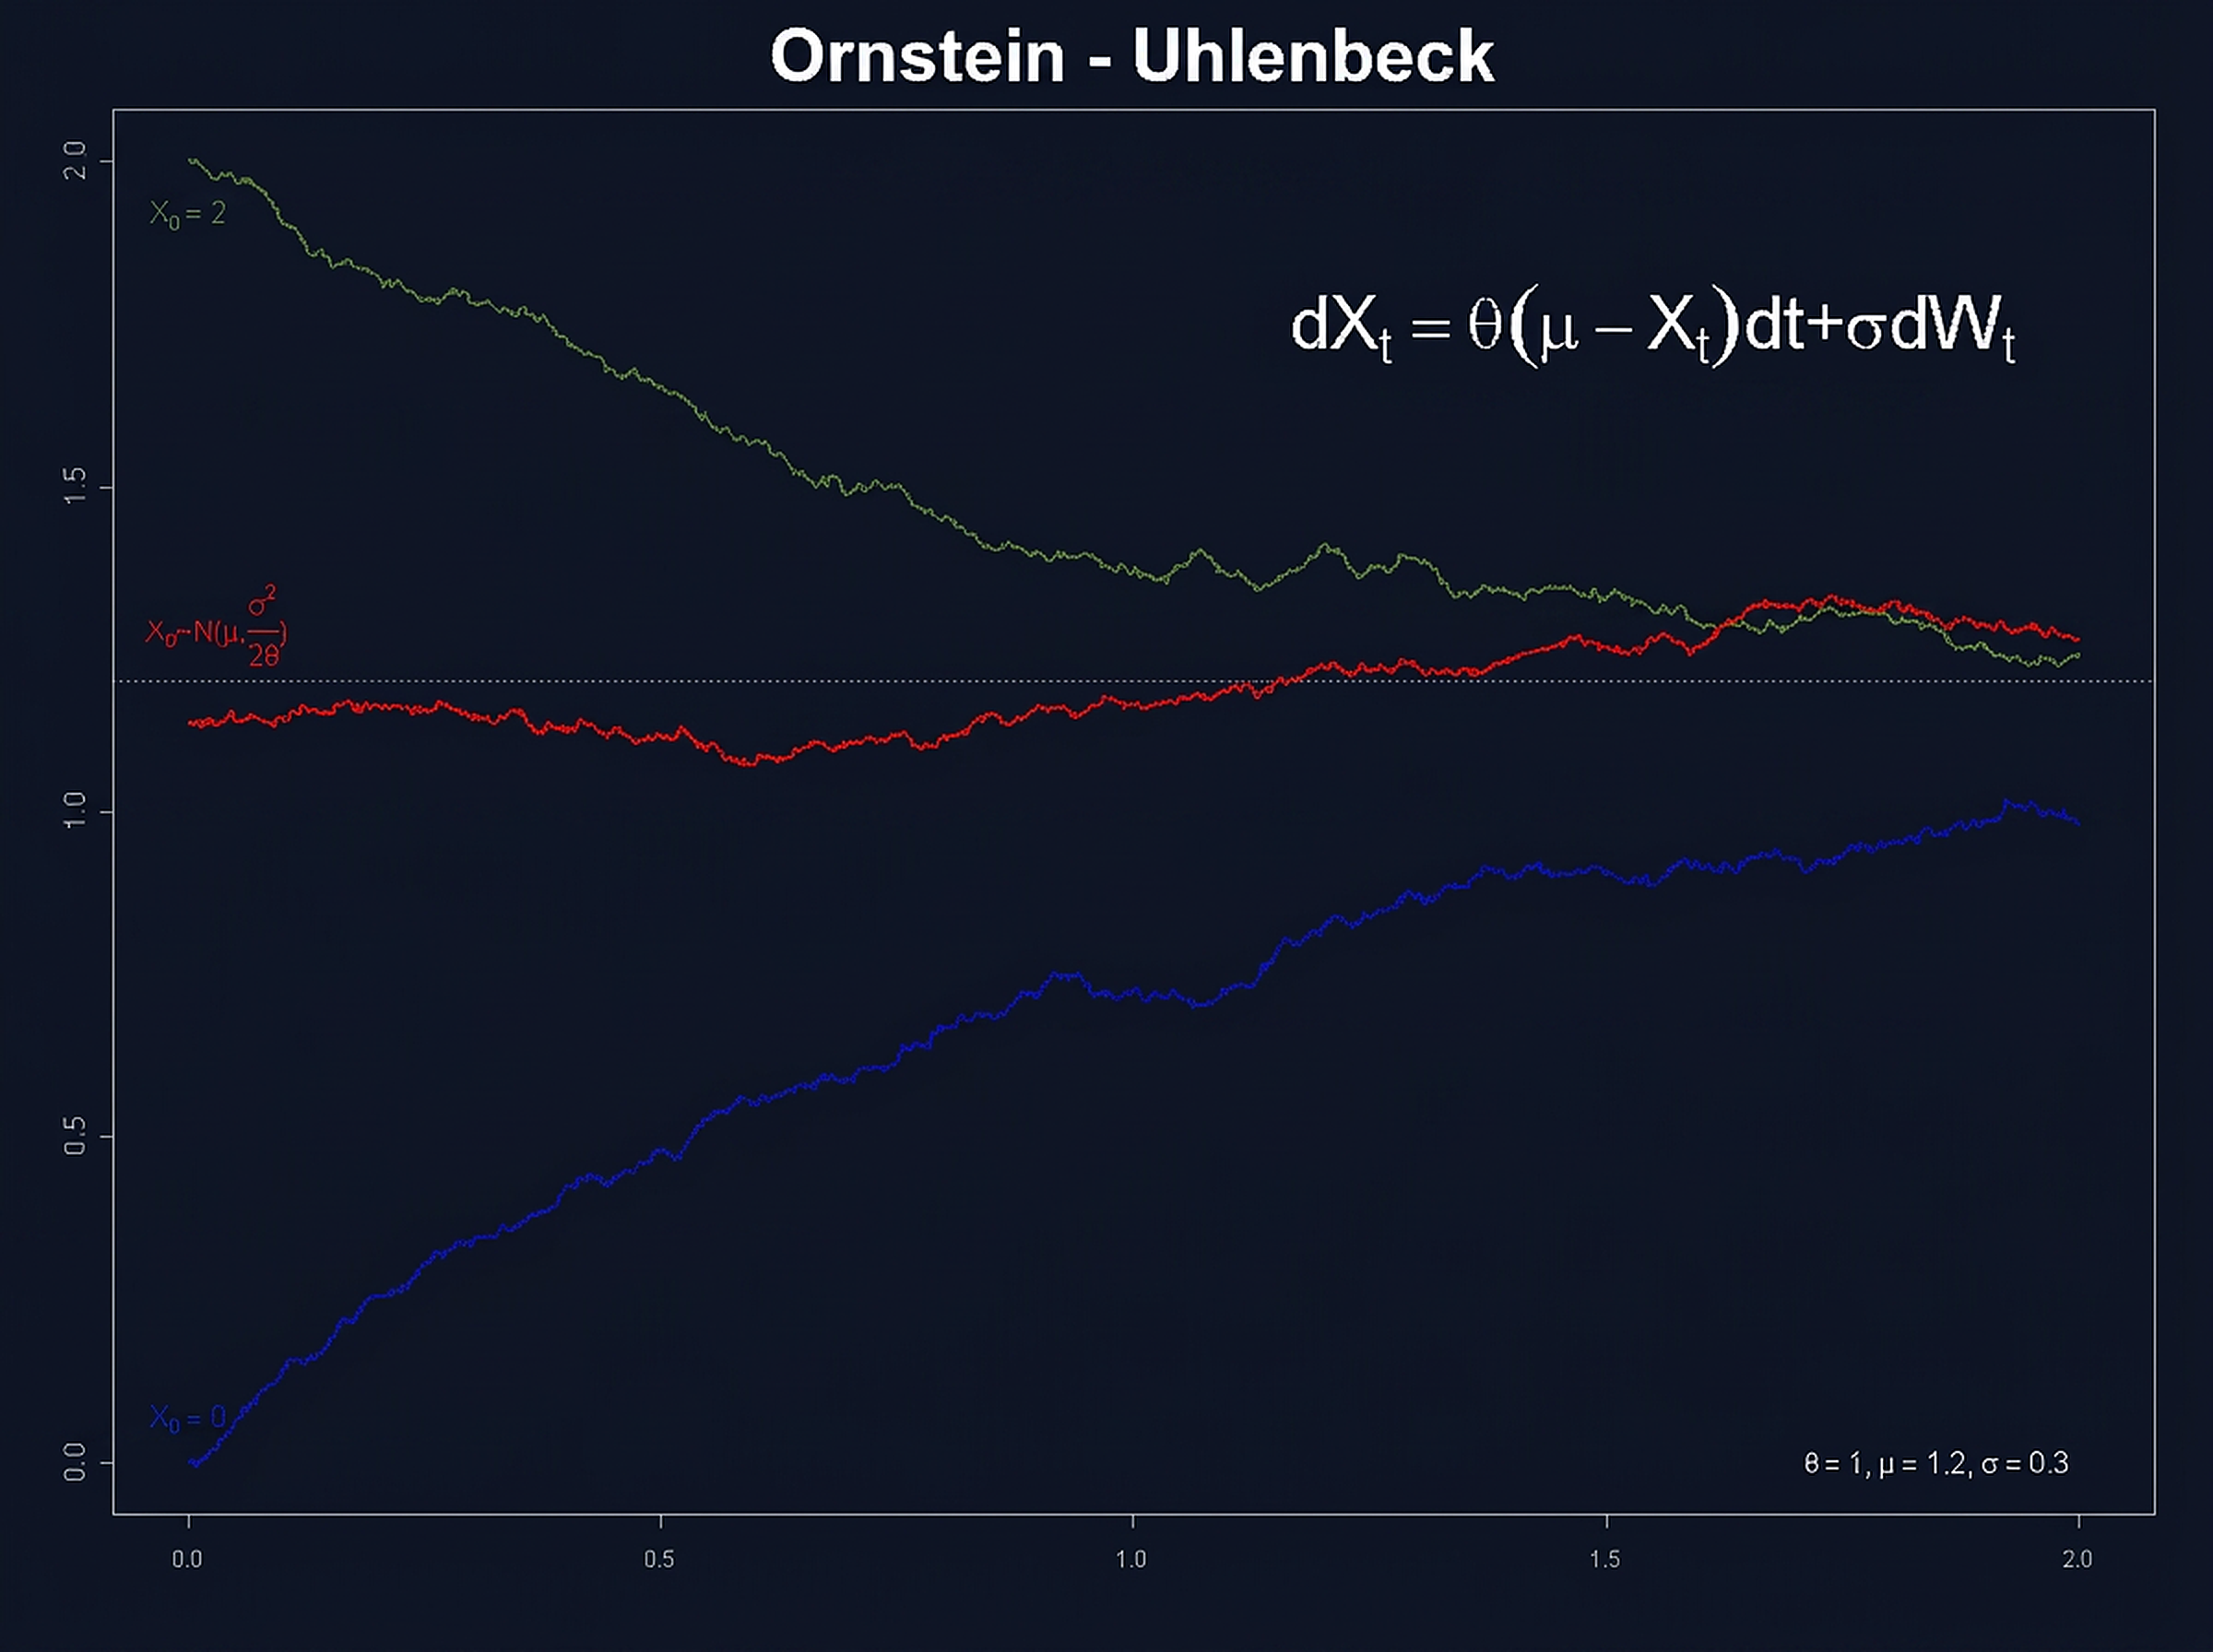
Two similar stocks trade at a spread. The paper models the unobservable "true" spread as a finite-state, mean-reverting Markov chain, while the observed spread is that hidden state plus additive Gaussian noise — a hidden Markov model rather than the usual ad hoc z-score band.
Because the state is hidden, ordinary regression on the spread does not apply. Calibration instead uses exact finite-dimensional recursive filters together with an EM-type algorithm to estimate the chain's transition rates and the noise variance from historical data.
Once calibrated, the model produces short-horizon predictions of the spread's distribution. When the observed spread diverges materially from the filtered equilibrium, we short the rich leg and buy the cheap one, unwinding as the spread reverts. The framework generalizes to any market quantities observed to be out of equilibrium.
Our implementation also corrects typos in the equations of the online algorithm in the original publication.
Parameter estimation
- › Shumway & Stoffer (1982) EM smoother — offline
- › Elliott & Krishnamurthy (1999) exact filter — online
References
- Elliott, R. J., van der Hoek, J. & Malcolm, W. P. (2005). "Pairs Trading." Quantitative Finance, 5(3), 271–276. https://doi.org/10.1080/14697680500149370
- Open-access copy: https://openresearch-repository.anu.edu.au/handle/1885/84862