// publications

Courses, books & talks

Research and teaching in quantitative trading by the NM FinTech team.
// book

Numerical Methods in Quantitative Trading

By Dr. Haksun Li, Dr. Waipun Ken Yiu, Dr. Kevin Haoyu Sun

NM FinTech Limited

© 2013–2020 Numerical Method Incorporation Limited. All rights reserved.

// course

Introduction to Quantitative Trading Strategies

Taught by. Textbook: Numerical Methods in Quantitative Trading.

A trader usually starts with an intuition or a vague trading idea. Using mathematics, s/he turns the intuition into a quantitative model for analysis, back-testing and refinement; once it passes rigorous statistical tests, the model is implemented for automatic execution. Quantitative trading is where mathematics and computer science meet.

Students study strategies from the academic literature — technical analysis, trend following, mean reversion, factor models, portfolio optimization and risk management — and gain hands-on experience through class projects, preparing them for front-office roles at hedge funds and banks.

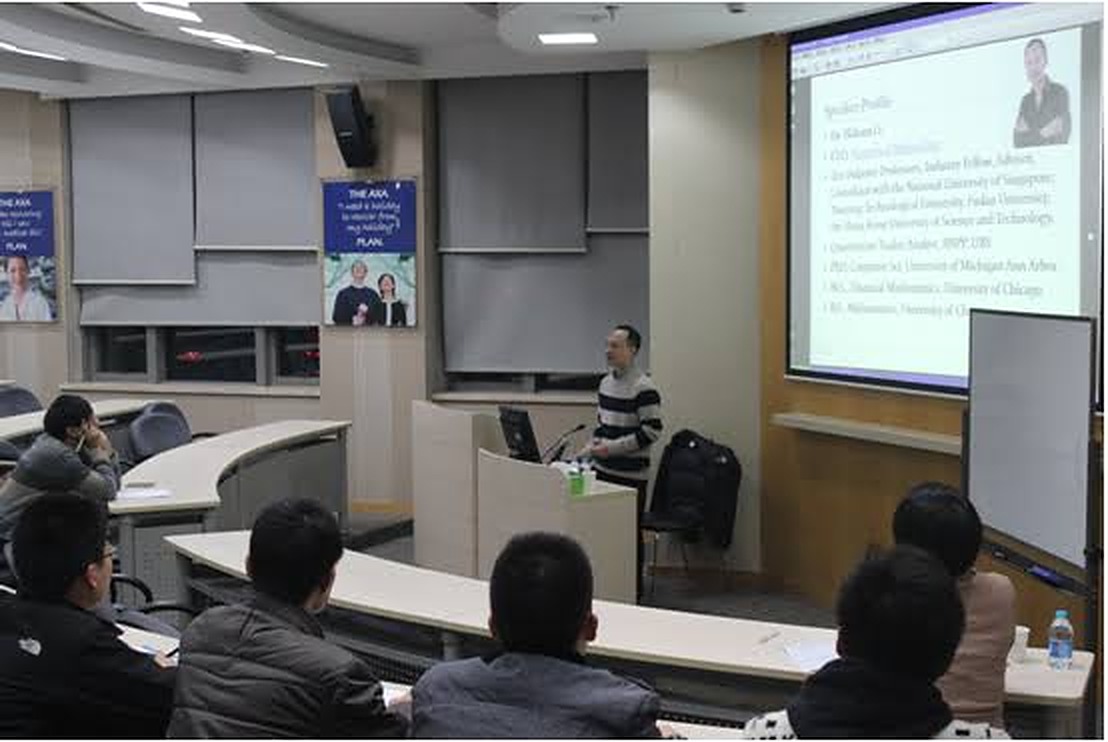
Prof. Haksun Li lecturing at Peking University
PROF. LI AT PEKING UNIVERSITY

Course outline

Offered at

  • M.Sc. in Financial Mathematics, Hong Kong University of Science and Technology — Sep–Dec 2015; Dec 2011; Jan–May 2013
  • 复旦大学经济学院: 算法交易 (Fudan University) — Nov 2011, Nov 2013
  • NTU-SGX Centre for Financial Education — Jul–Aug 2011
  • Nanyang M.Sc. in Financial Engineering, FE8827, NTU — Mar–Apr 2011, 2012
  • M.Sc. in Quantitative Finance, QF5205, National University of Singapore — Feb–Apr 2011, 2012
// presentations

Presentations

Beyond Markowitz Portfolio Optimization

Dr. Haksun Li · PDF

Markowitz's 1952 theory is elegant but of little practical value: it assumes known future means and covariances, which are very hard to estimate. This talk surveys the latest portfolio-optimization technologies and how to apply them profitably in practice. Also delivered in Chinese as 资产配置技术的新突破 (李克辛 教授).

  • › CFA, Beijing — Jul 4, 2017
  • › Beijing Wealth Management Association — Jul 5, 2017
  • › Fudan University summer seminar on quantitative finance — Jul 11, 2017
  • › QuantCon Singapore — Nov 29, 2017

Quantitative Trading as a Mathematical Science

Dr. Haksun Li · PDF

Quantitative trading justifies strategies with mathematical reasoning: P&L distributions and risks can be deduced before betting the first dollar, and strategies refined by making assumptions more realistic. It is also a driver of mathematical innovation — coupled HJB equations for optimal trend timing, semi-definite programs for sparse mean-reverting baskets, and quasi-variational inequalities for optimal order placement.

  • › Stanford-Tsinghua-PKU Conference on Quantitative Finance and Risk Management — Mar 31, 2017
  • › QuantCon Singapore — Nov 11, 2016

Algorithmic Trading as a Science

Dr. Haksun Li · PDF

How to generate and analyze trading strategies scientifically, distinguishing justifiable models from unscientific ones. Mathematics makes market intuition precise; programming turns equations into P&L.

  • › NTU-SGX Centre for Financial Education, Nanyang Technological University — Feb 26, 2011

My Experience with Algorithmic Trading

Dr. Haksun Li · PDF

Industrial experience in algo trading: IT infrastructure, trading-system design, strategy creation and automation, practical pitfalls, and a sample strategy. Technology decides the arms race — computer science matters as much as mathematics.

  • › School of Information Systems, Singapore Management University — 2010
  • › M.Sc. in Quantitative Finance, National University of Singapore — 2010
// conferences

Conferences & invitations

  • 中国金融期货交易所:债券期货交易 (China Financial Futures Exchange)Aug 15, 2013
  • 北大演讲:量化投资与交易的科学之道 (Peking University)Jun 1, 2013
  • 4th Annual Trading Architecture AsiaAug 29–31, 2012
  • Battle of the QuantsDec 14–15, 2011
  • Workshop on Recent Developments of Financial Mathematics (REDFIN2011)Dec 13, 2011
  • HKU-HKUST-Stanford Conference in Quantitative FinanceDec 9–10, 2011