NM Risk Management System
PortOptim, the NM Risk Management System, lets portfolio managers construct, optimize and backtest quantitative equity portfolios by drag-and-drop. Every step of the quant workflow is a configurable module — no programming required.
Start free trial →Intelligent portfolio management
Online platform
Browser-based GUI with documentation and tutorial videos. No programming needed.
Risk factor database
Hundreds of daily-updated US and China equity factors, ready to plug into any model.
Personalized optimization
Automatic portfolio construction based on each investor's needs and risk appetite.
Source code & API
Source code available for customization; host the system securely on your own infrastructure.
Watch the walkthrough
From universe to risk report
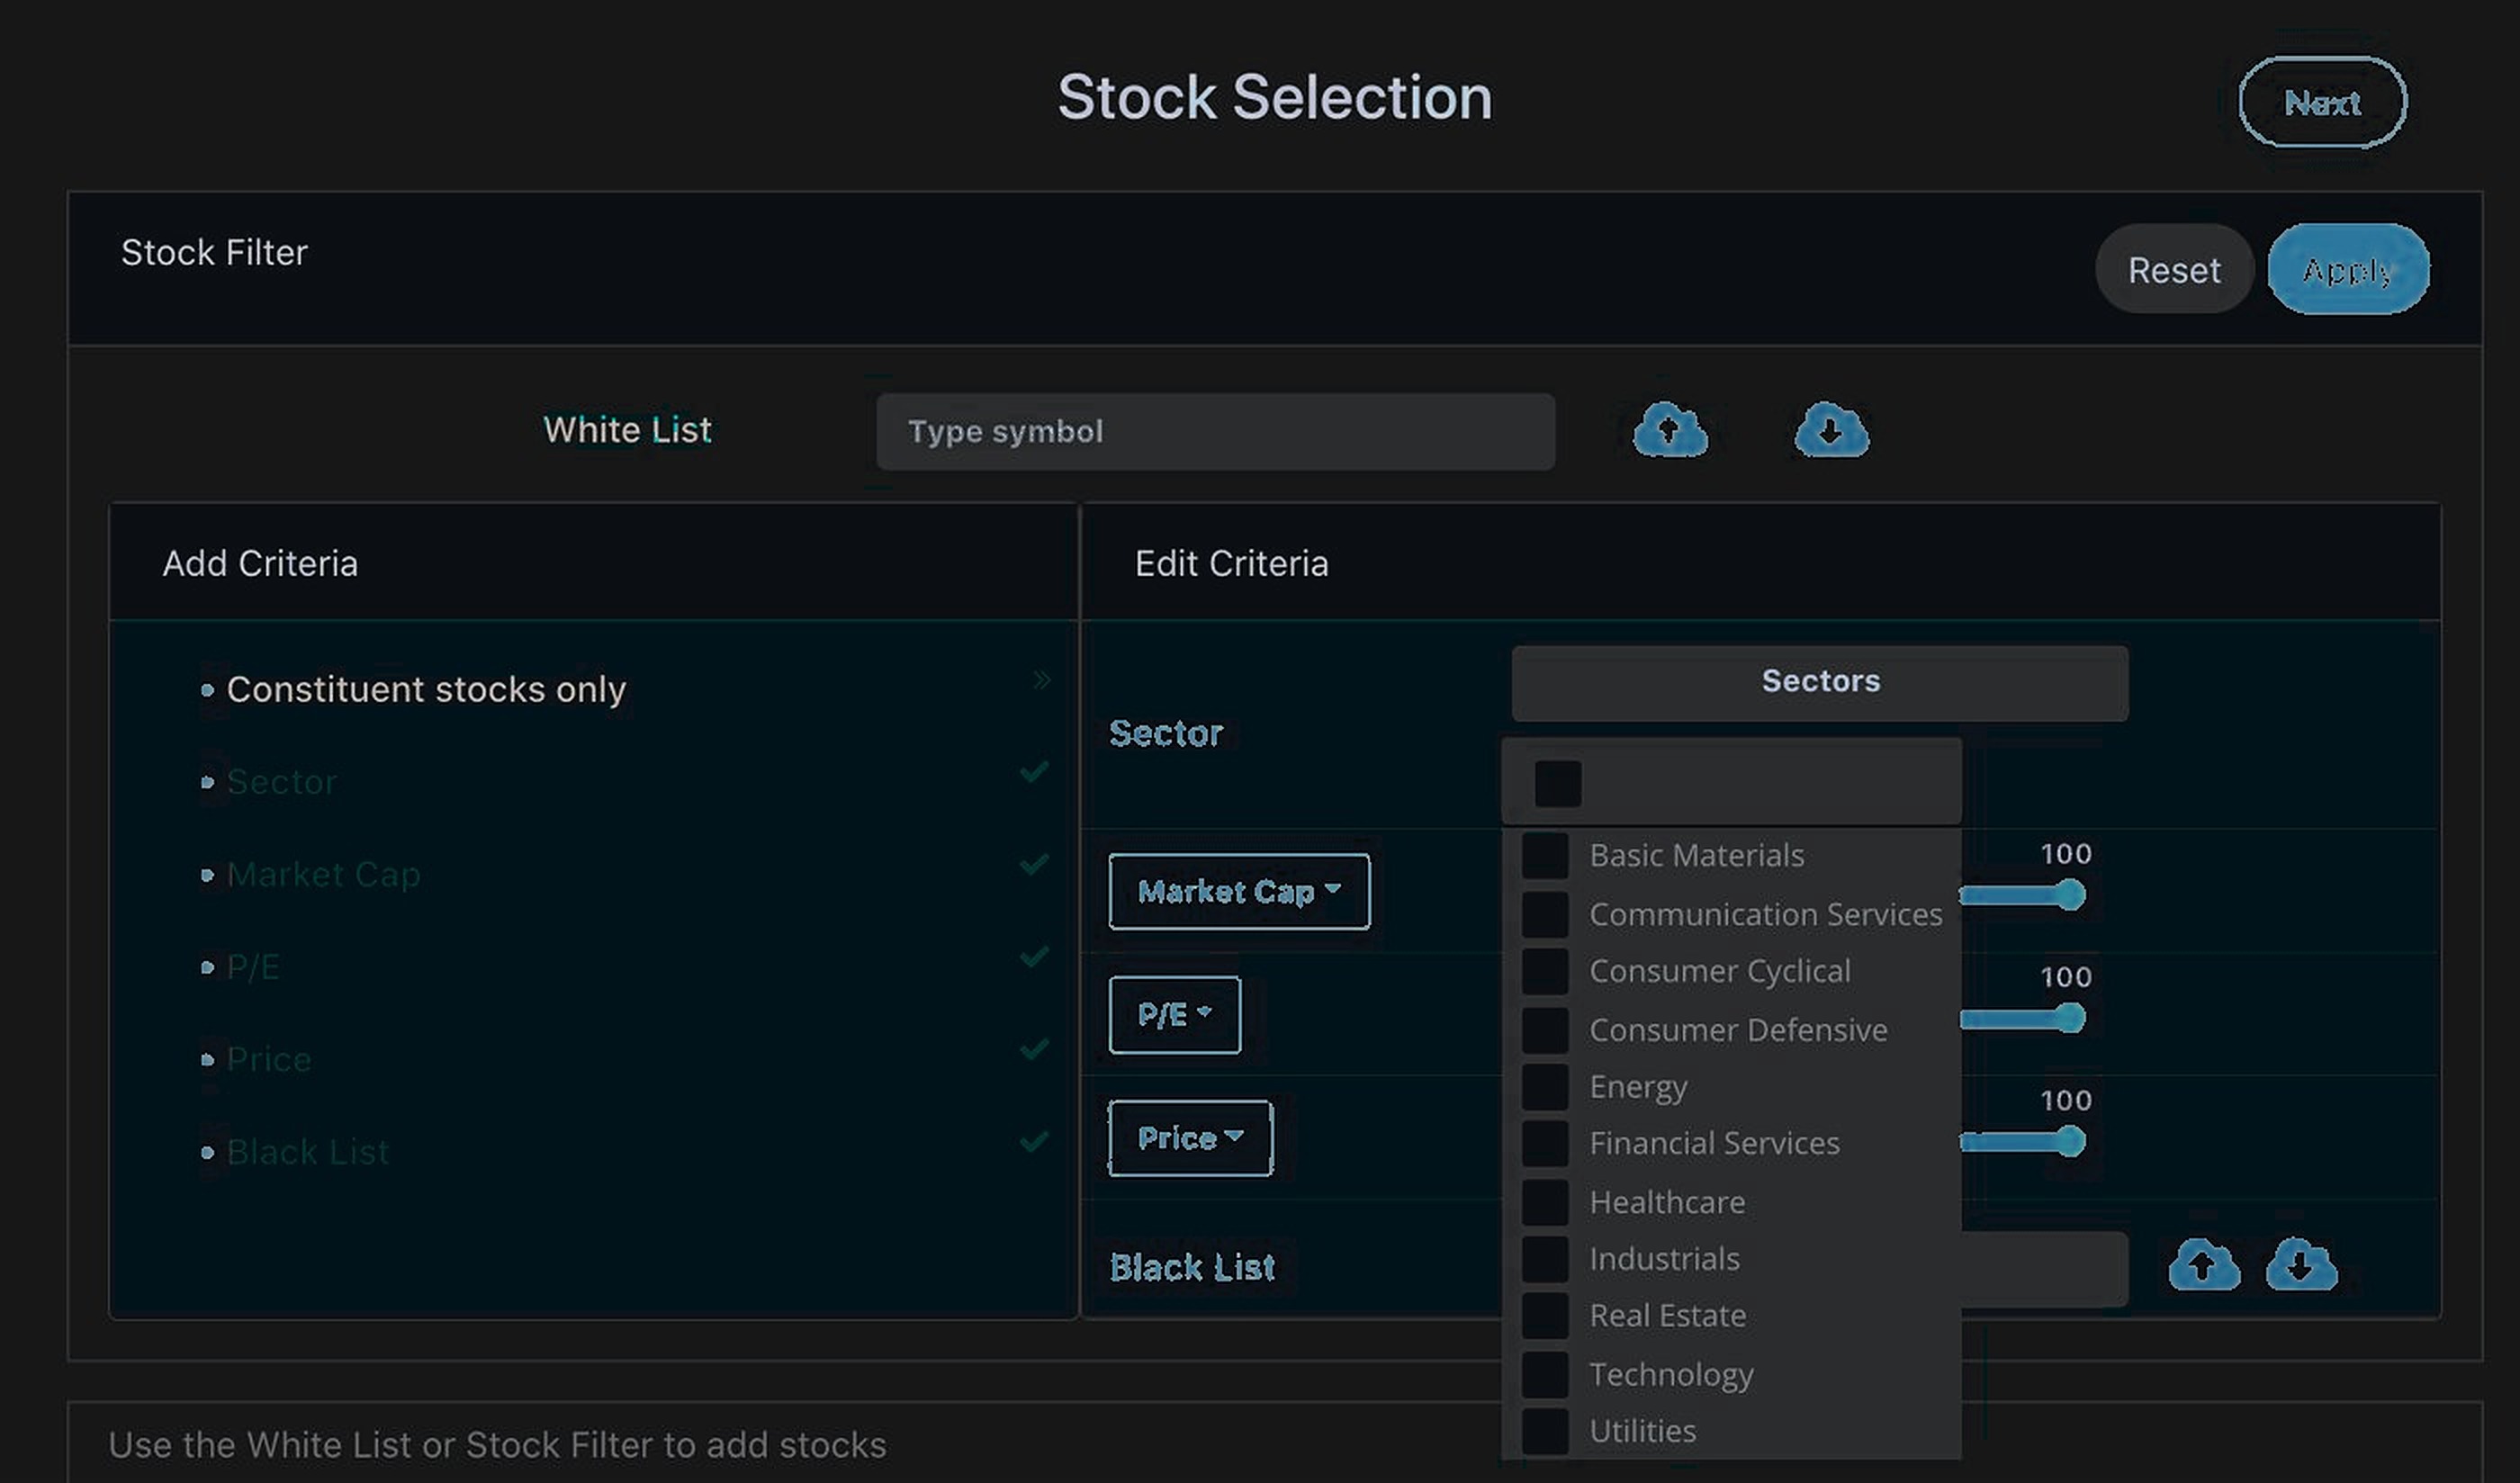
Configure the universe
Select the investable stocks, benchmark, rebalancing frequency and backtest window as a reusable configuration.
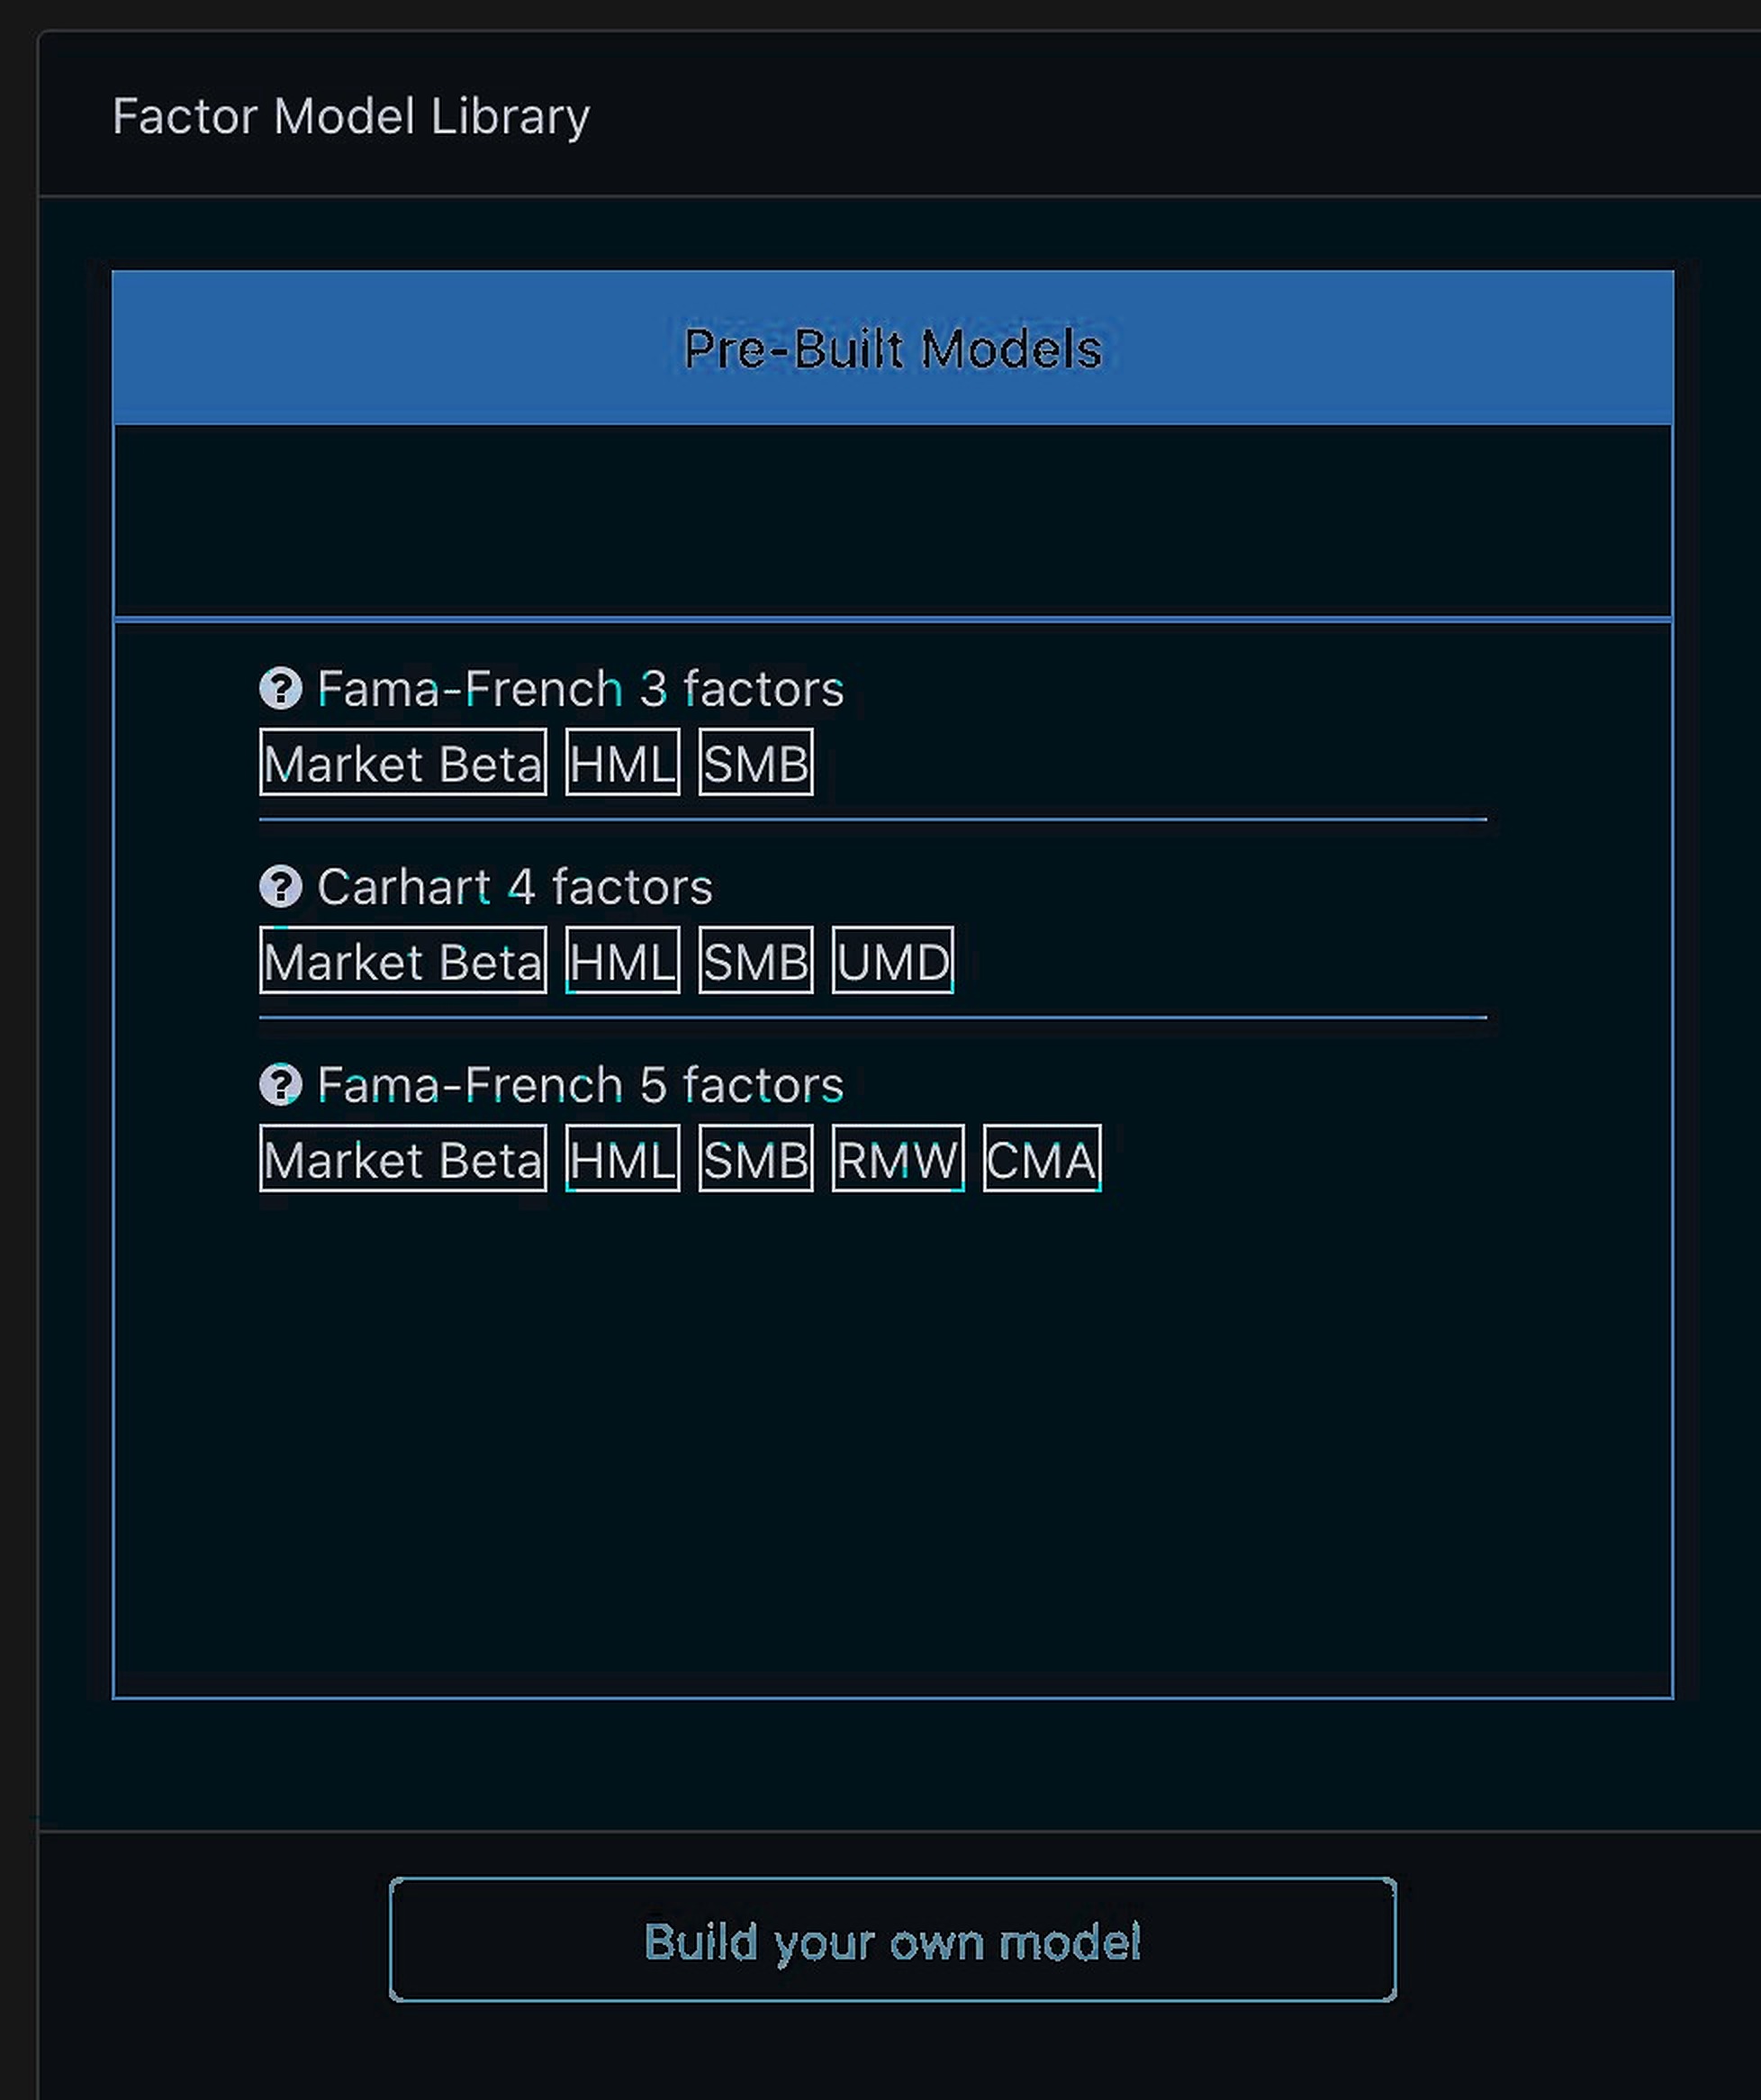
Estimation models
Pick a returns estimation model and a covariance-matrix estimation model independently — e.g. a Fama-French 3-factor model with market beta, HML and SMB — or add your own factors.
Position limits & constraints
Set weight bounds, long-only or long-short rules, sector and turnover limits that the optimizer must respect.
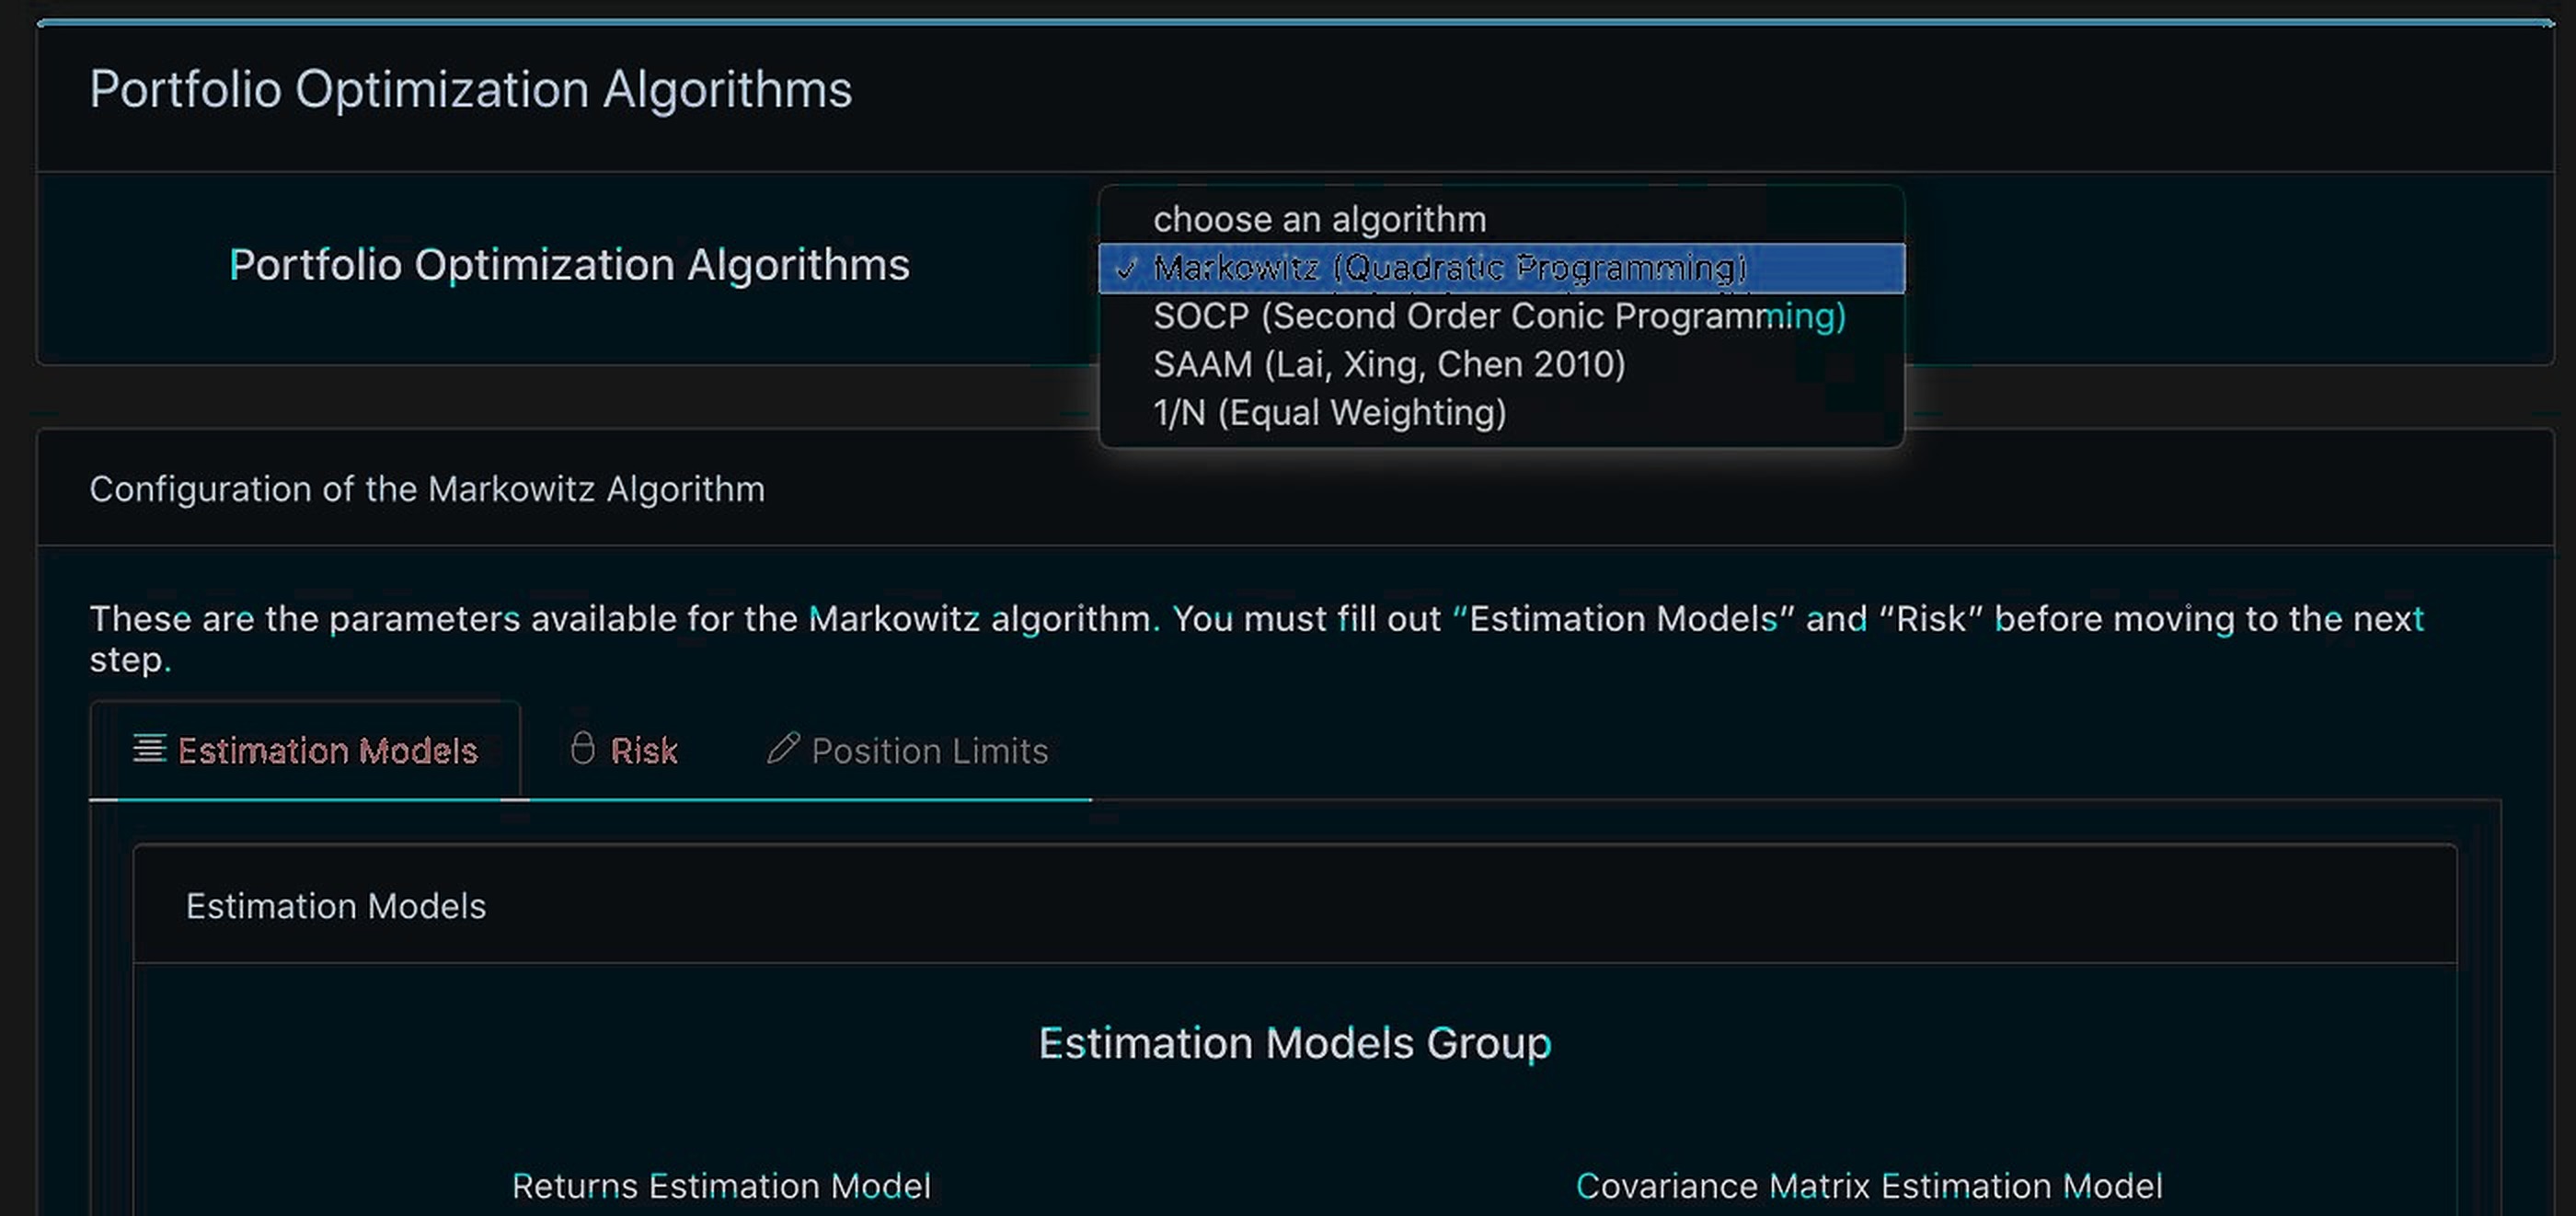
Optimize
Choose an objective from classic Markowitz mean-variance to large-scale second-order cone programming (SOCP).
Backtest & reports
Run the strategy through history and get performance, attribution and risk reports for every configuration side by side.
- ›No-code, browser-based workflow
- ›Mix and match return, covariance and optimization models
- ›Factor models including Fama-French
- ›Hosted by NM FinTech or deployed on your own infrastructure
Portfolio & risk management reports
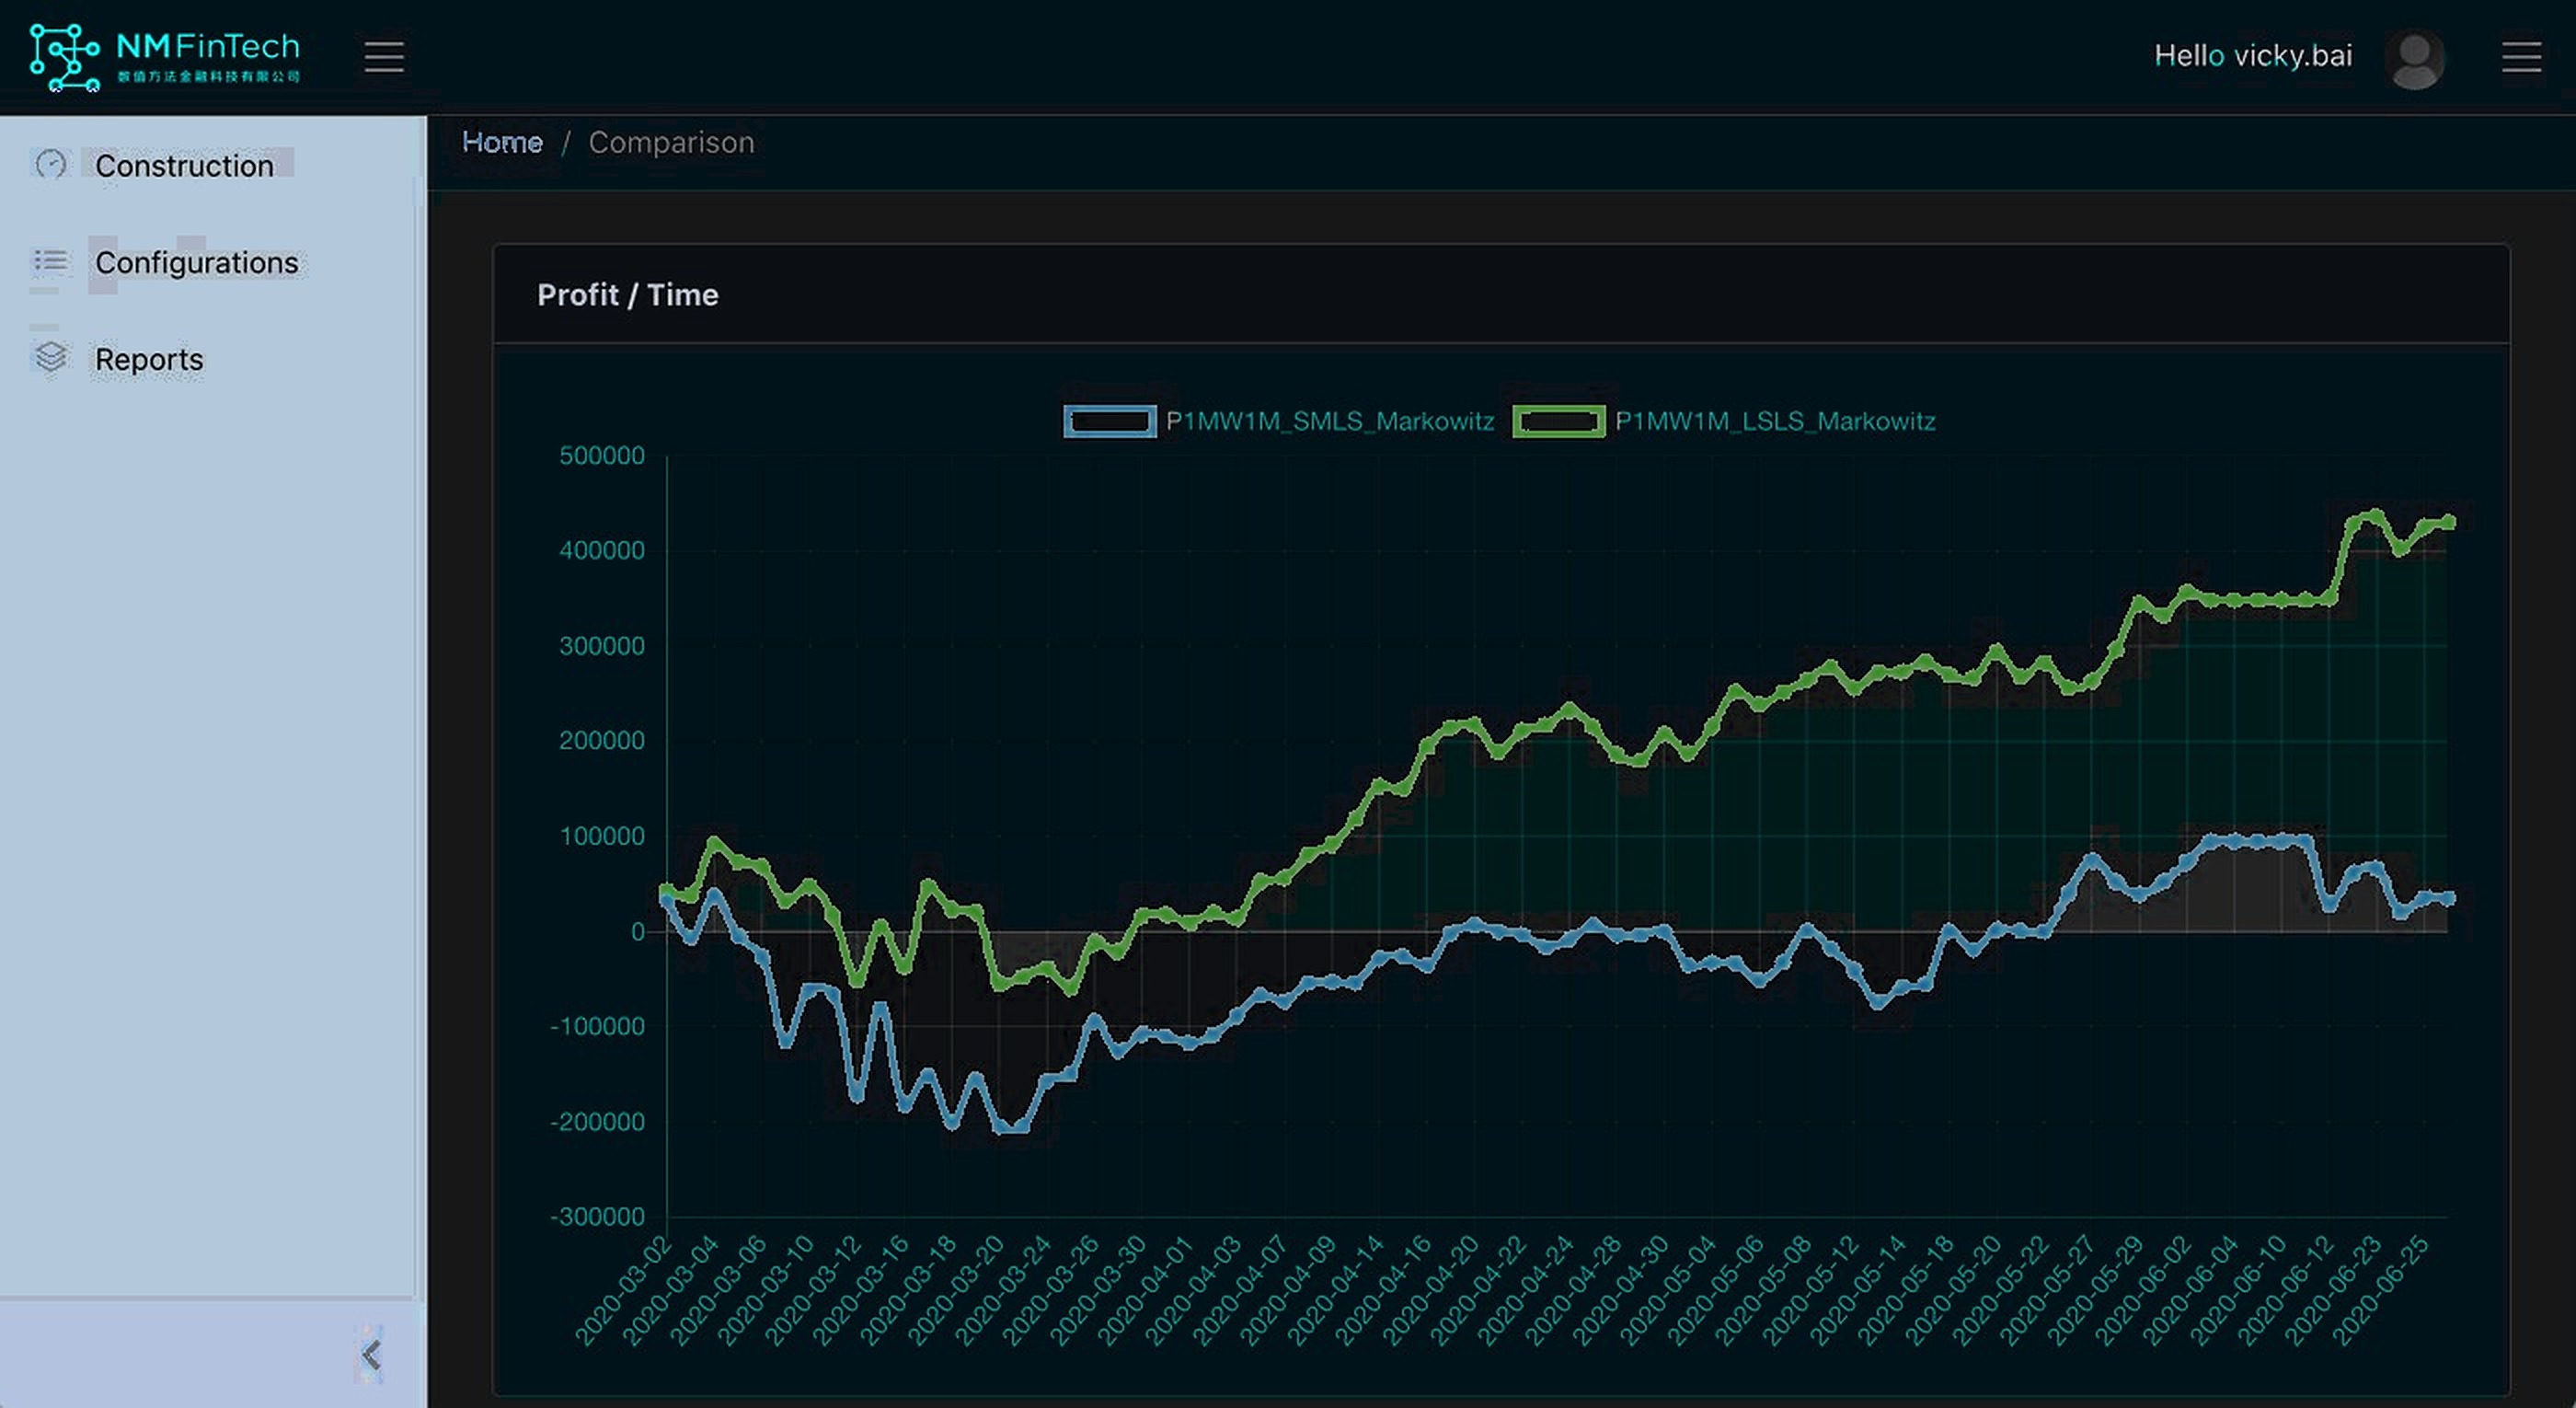
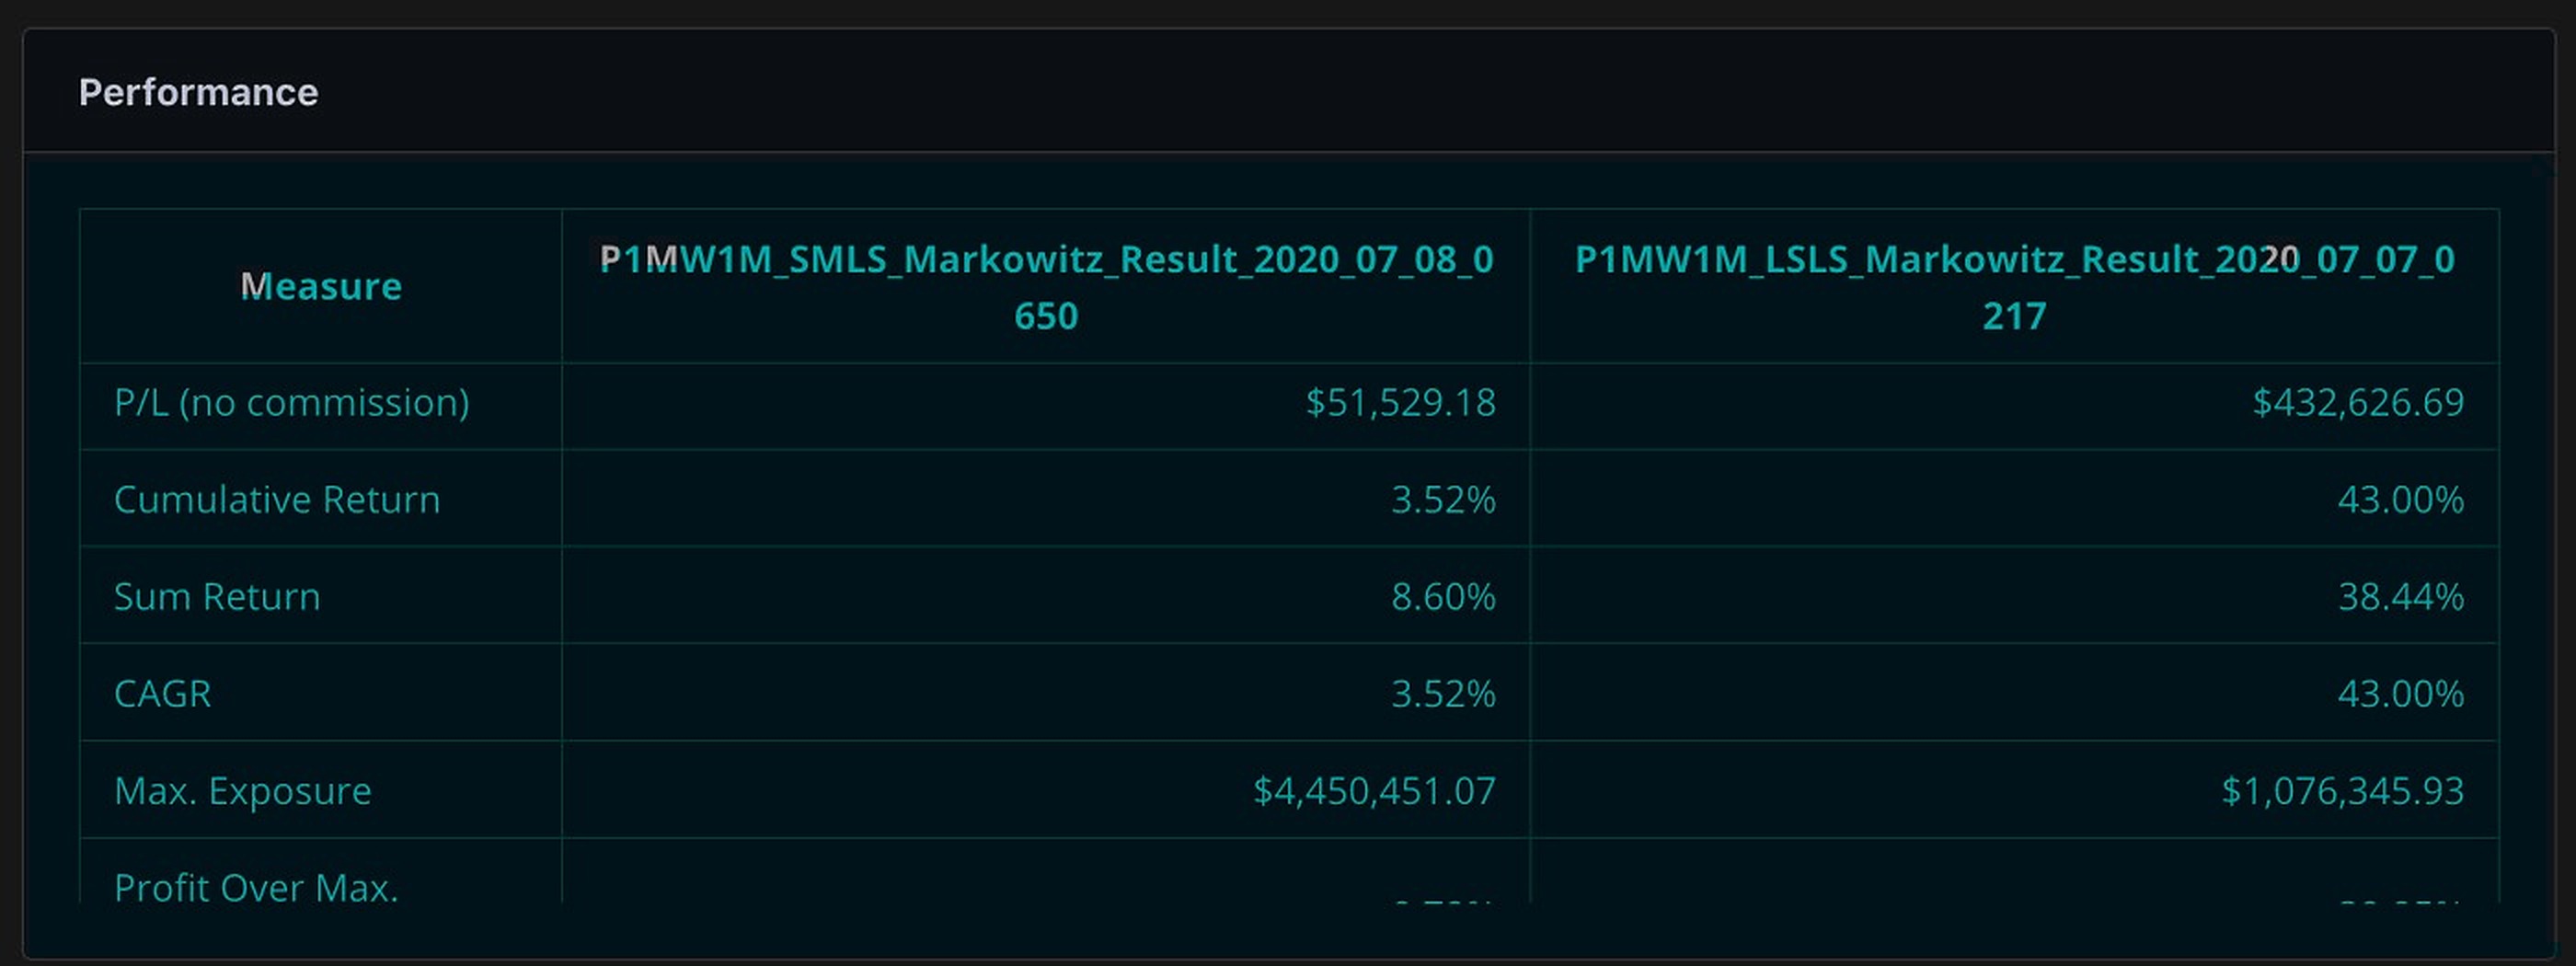
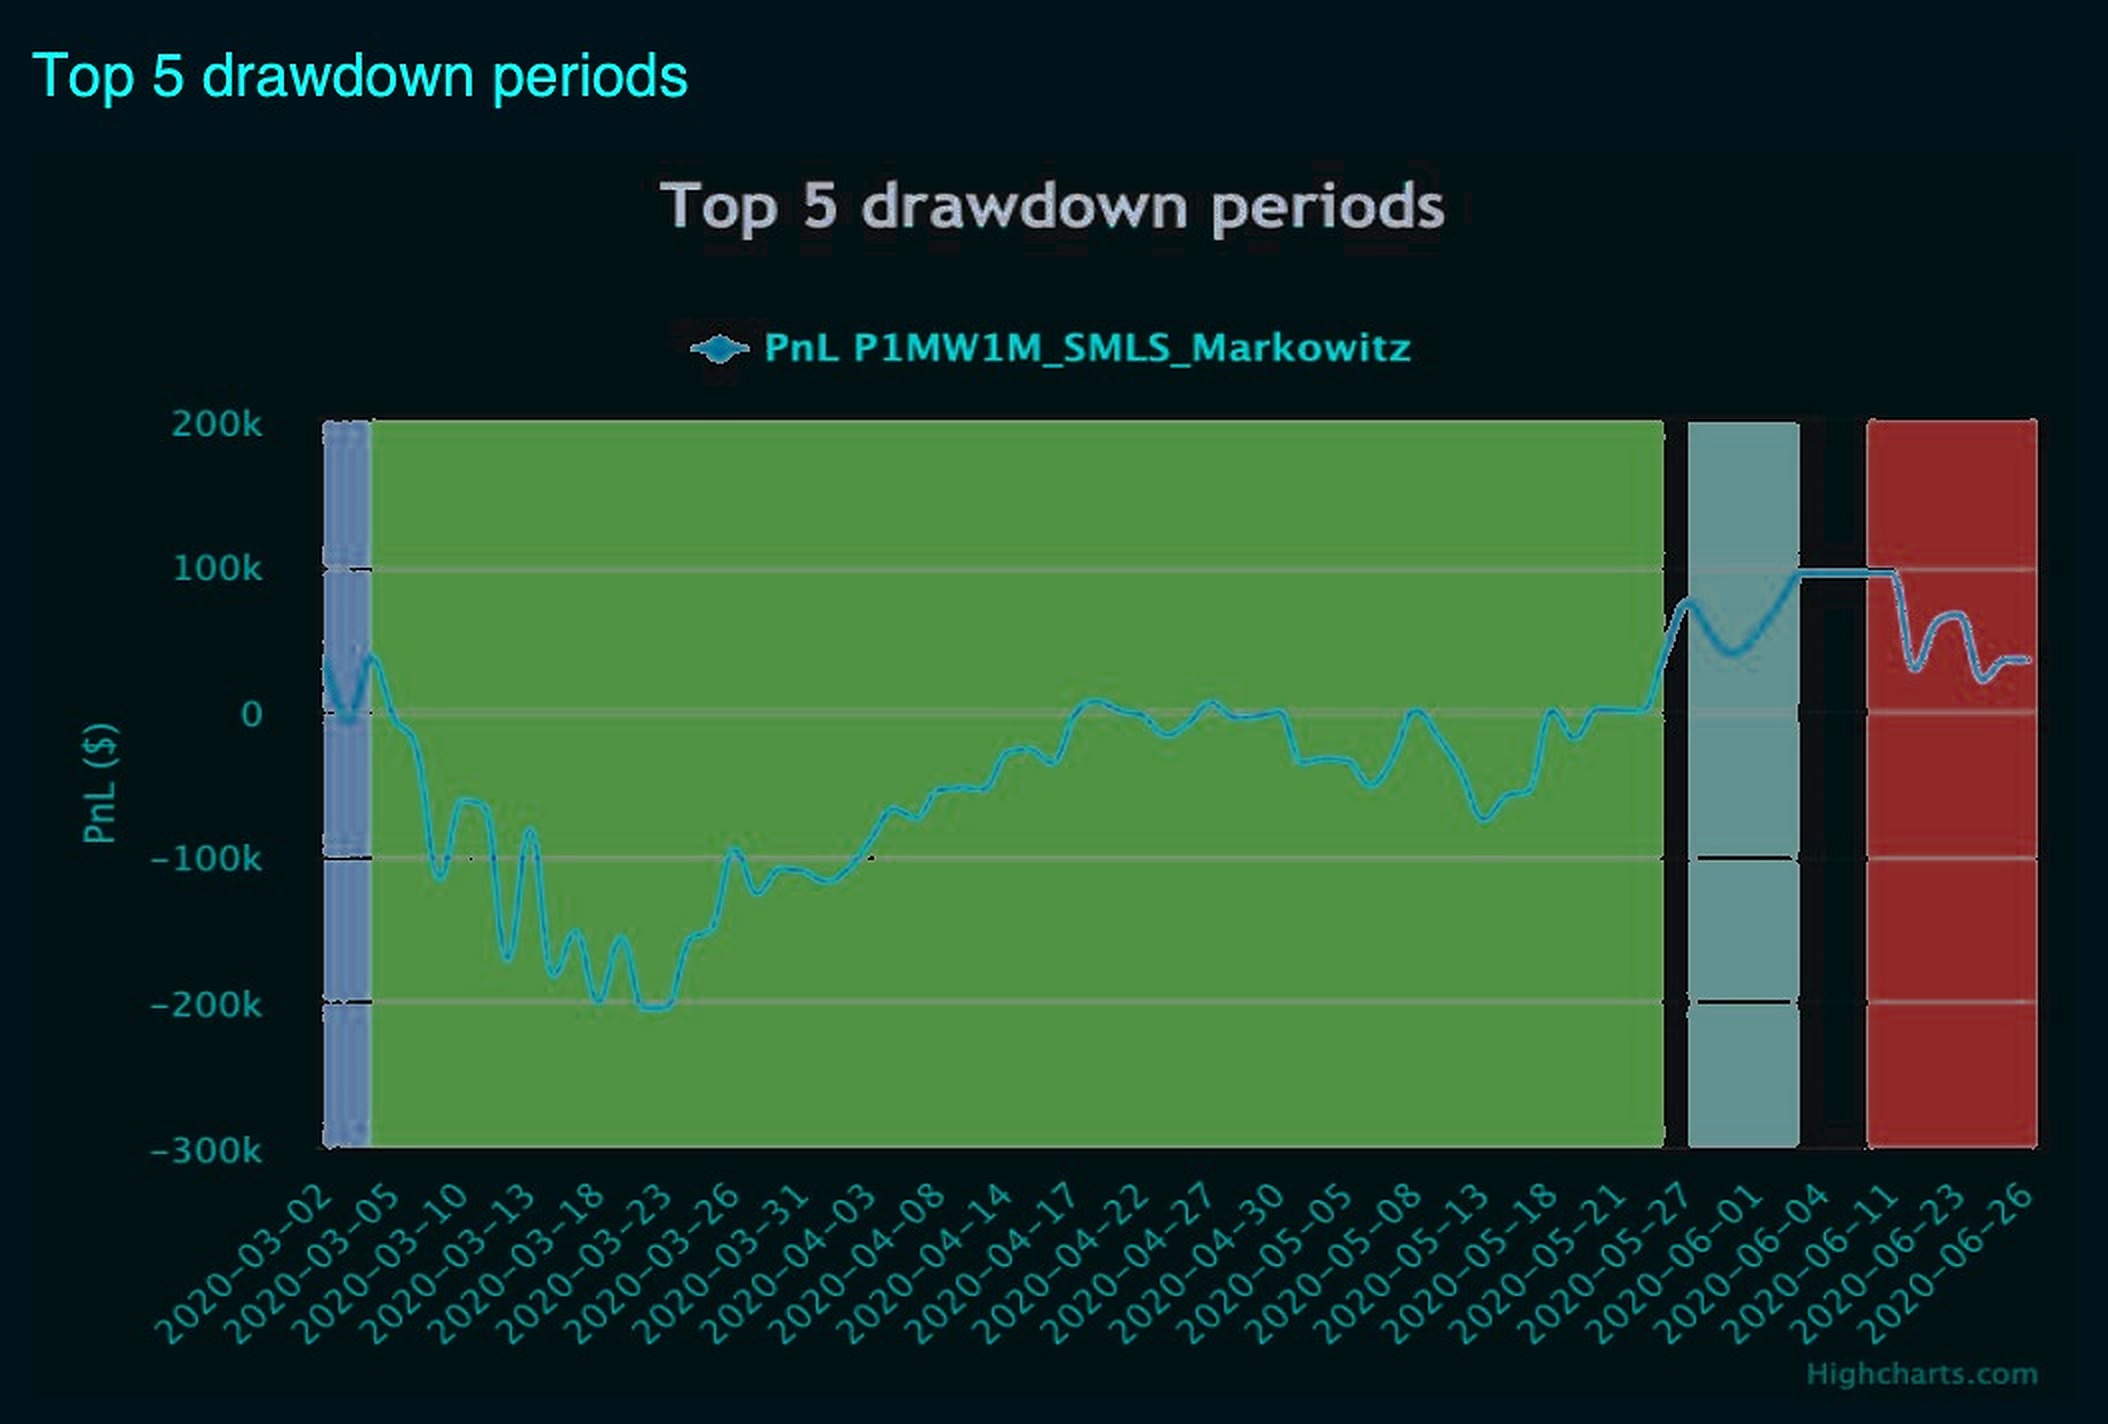
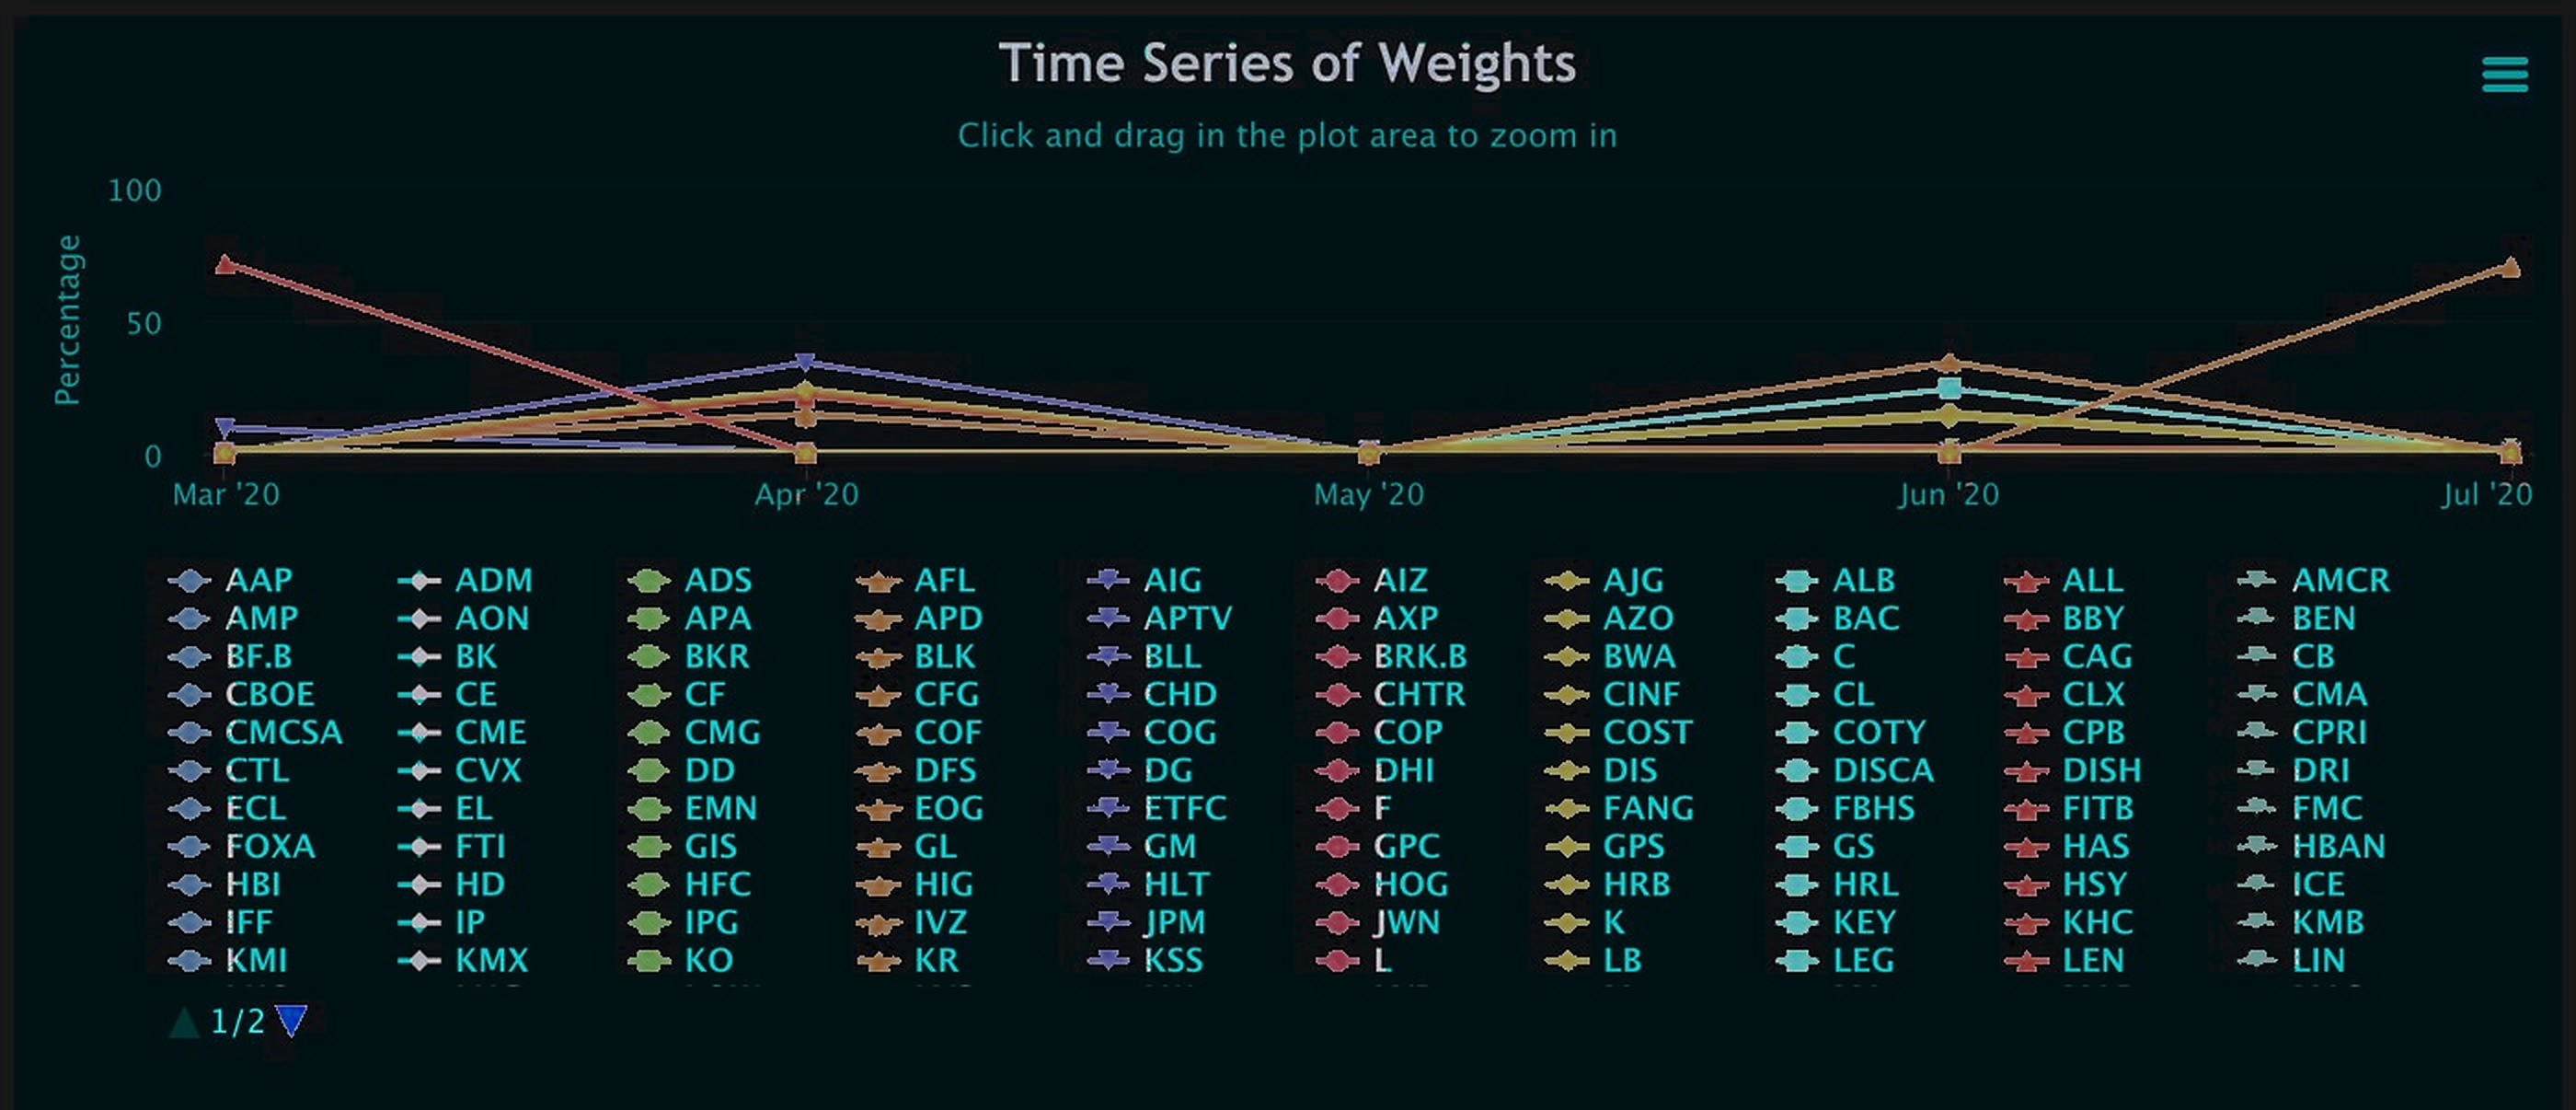
Every backtest produces analytical charts, profit & loss plots, vital performance statistics, weights over time and the full trade list — with configurations compared side by side.
- ›P&L and cumulative return comparison
- ›CAGR, exposure and drawdown statistics
- ›Top drawdown periods
- ›Time series of weights and trades
Stochastic Asset Allocation Model (SAAM)
Historical data is only one realization of the market distribution. SAAM optimizes against the true underlying probability distribution rather than one observation — addressing the hardest problem in Markowitz-based models: estimating expected returns and the covariance matrix.
- ›No overfitting; robust to limited or missing data
- ›Index alternatives: SPX, CSI, HSI, FTSE, Euronext, DAX, NIKKEI, Nifty, crypto
- ›Partial indices: cardinality constraints track an index with a subset of stocks
- ›More effective hedging, robo-advice and fund ranking
Risk factors
A high-performance, real-time factor database with fully independent intellectual property, covering listed US stocks (major exchanges and OTC) and 3,500+ Shanghai and Shenzhen stocks.
- ›Daily update; quarterly fundamentals converted to daily series
- ›Report release date + 2 trading days used to avoid look-ahead
- ›Outliers, missing points and meaningless ratios (e.g. negative P/E) handled
- ›TTM income/cash-flow factors; quarterly and yearly growth rates